
Data breaches keep getting worse, not better. Equifax, T-Mobile, Marriott, the National Public Data leak, every health insurer in the country at some point. Your name, Social Security number, and date of birth are almost certainly sitting in at least one hacker database already. The single best free defense is a credit freeze at all three bureaus, and since 2018 it has been free under federal law.
Key takeaways
- Freezing your credit is free at all three bureaus under the 2018 Economic Growth Act.
- A freeze blocks new accounts being opened in your name. It does not stop fraud on existing accounts.
- You can freeze and unfreeze online or by phone in minutes. No more mailing forms.
- Freeze the big three plus NCTUE, ChexSystems, and Innovis for full coverage.
- Set up a password manager to store your freeze PINs and unfreeze codes.
What a credit freeze actually does
A credit freeze, sometimes called a security freeze, locks your credit file at the bureau. When a lender tries to pull your report to open a new account in your name, they get a no-hit response and the application dies. Existing accounts, autopay, employer verifications, and your own credit score apps still work normally.
Think of a freeze as locking your front door at night. It does not stop every kind of theft, but it stops the casual ones, which is most of them.
When you should freeze your credit
- You were notified your data was in a breach (basically everyone in the US by now).
- Your wallet, mail, or laptop was stolen.
- You have already been a victim of identity theft.
- You are not planning to open new credit in the next few months.
- You want a baseline layer of defense even if you have not seen any specific incident.
Freeze vs. lock vs. fraud alert
These three terms get confused constantly.
- Freeze is the federal-law version. Free. Strongest protection. You must unfreeze for a hard pull.
- Lock is a bureau product. Often sold inside a paid monitoring bundle. Convenient toggling but weaker legal guarantees.
- Fraud alert is a one-year flag telling lenders to verify identity. Does not block pulls. Free.
Use the freeze. It is free, it is the strongest, and it is backed by federal law.
Step-by-step: freeze your credit at the big three
Plan on 15 to 30 minutes total. You will need your Social Security number, date of birth, current and recent addresses, and an email address.
Equifax
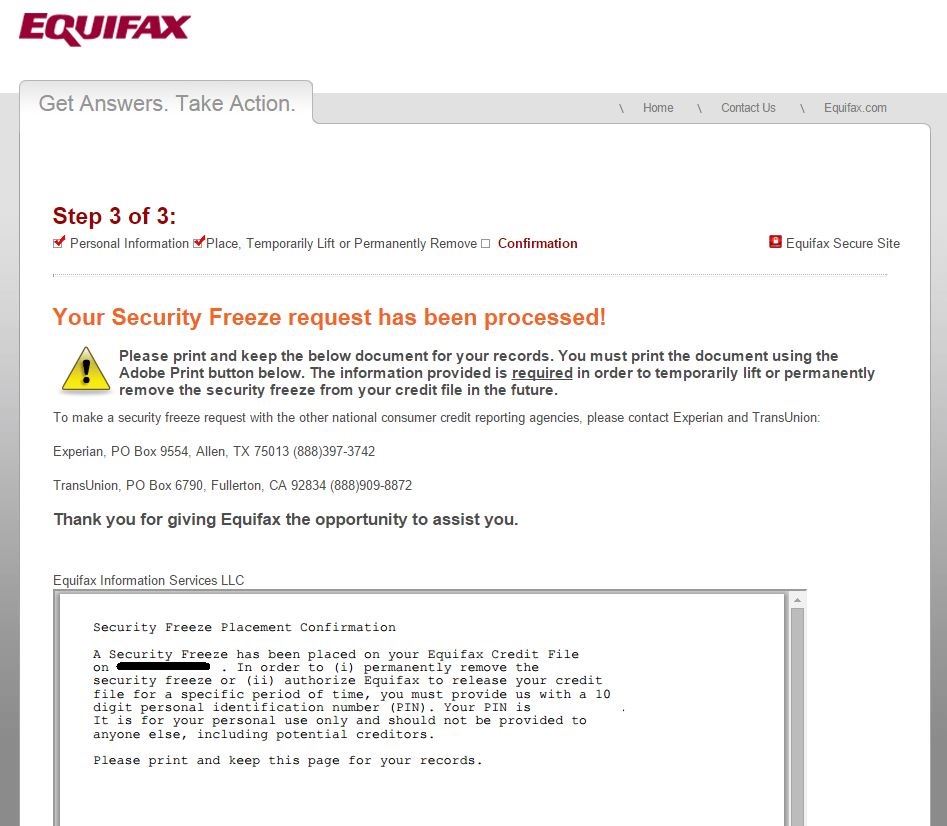
Go to equifax.com/personal/credit-report-services/credit-freeze or call 1-800-685-1111. Create a myEquifax account, verify identity through their question set, then click Place a Freeze. Save the confirmation page.
Experian
Go to experian.com/freeze or call 1-888-397-3742. Create an account, verify, and place the freeze. Experian will give you a PIN. Save it.
TransUnion
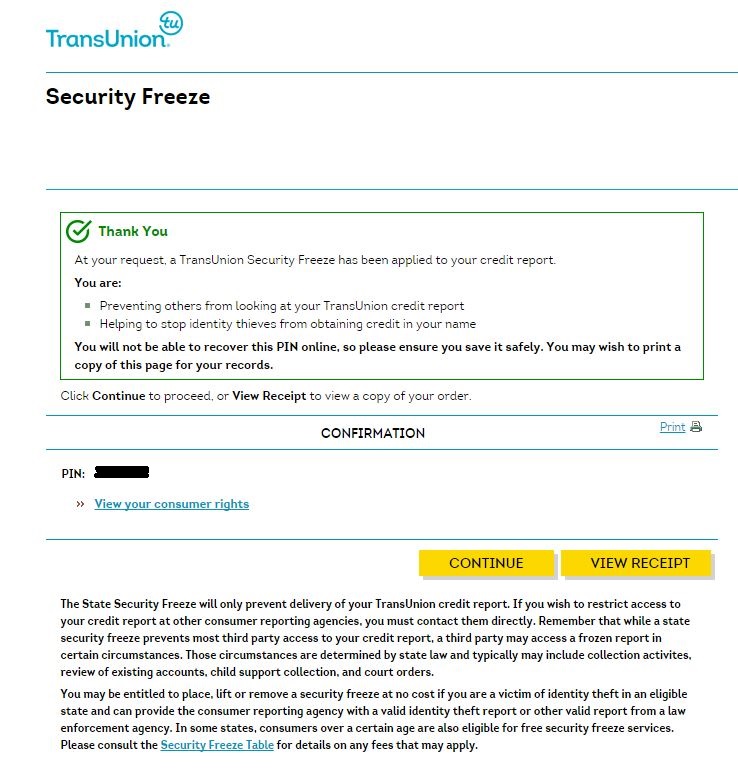
Go to transunion.com/credit-freeze or call 1-888-909-8872. Same flow. Create an account, verify, freeze.
The other bureaus people forget
Equifax, Experian, and TransUnion get all the attention, but a few specialty bureaus are used by phone carriers, banks, and check writers. Freeze these too.
- Innovis at innovis.com. A fourth general-credit bureau that some lenders pull.
- NCTUE at nctue.com. The National Consumer Telecommunications and Utilities Exchange. Used when fraudsters open phone or utility accounts.
- ChexSystems at chexsystems.com. Used by banks when you open a checking account.
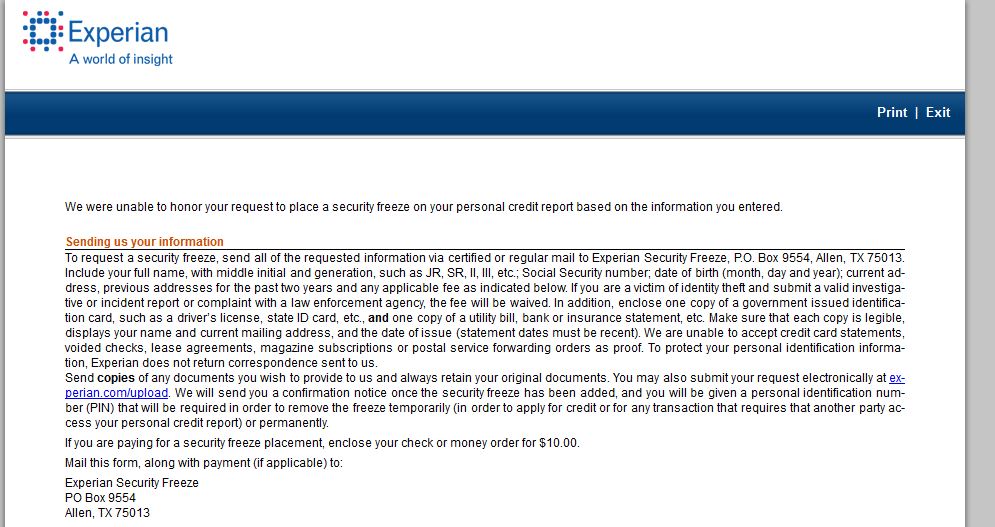
What if identity verification fails?
If the bureau cannot verify you through their question set, you will have to submit by mail with copies of a government ID and a utility bill. Annoying but only happens once. The screenshot below shows the kind of manual form Equifax used to ask for.
What changes for you after the freeze
- You will not be able to open new credit, get a new phone line, or sometimes even switch utility provider without temporarily lifting the freeze.
- You can do a temporary lift for one day, one week, or any window you choose.
- Existing credit cards, mortgages, autopay, your credit-monitoring app, and pre-approved offer suppression all keep working.
- Your credit score still updates normally.
Storing your unfreeze info safely
Use a password manager. Save each bureau's login, recovery email, and PIN as a separate entry. If you get hit with a fraud attempt at 11 p.m. on a Sunday, you want to be one tap away from lifting a freeze, not digging through paper.
What a freeze does not protect against
A freeze stops new account fraud. It does not stop:
- Charges on your existing cards (use chip plus virtual card numbers).
- Tax refund fraud (file early, set up an IRS IP PIN).
- Medical identity theft (review explanation-of-benefits statements).
- Account takeover via password reuse (use unique passwords and 2FA).
FAQ
Does freezing my credit hurt my credit score?
No. A freeze has zero effect on your score. The bureaus continue to update your file normally.
How much does a credit freeze cost in 2026?
Free at all three bureaus, by federal law, for every consumer in the US. The Economic Growth, Regulatory Relief, and Consumer Protection Act of 2018 made it permanent.
How long does a freeze stay in place?
Indefinitely, until you lift it. There is no expiration.
How fast can I lift a freeze when I actually need credit?
Online or via app, the lift is effectively instant. Plan to do it 15 minutes before you apply for a loan or a phone line.
Can I freeze my children's credit?
Yes, and you should. Child identity theft is a fast-growing category and the kids will not check their report for 15 years. The bureaus have a separate process for minors that requires birth certificate and proof of custody.
Should I also pay for a credit monitoring service?
Probably not. A freeze is stronger than monitoring, and most monitoring features are duplicated by your bank app, your card issuer's alerts, and free services like Credit Karma. Save the $20 a month.
Comments (0)
Be the first to comment.
Leave a comment